The Hold Harmless Provision and Its Hidden Limitations
Federal law contains a protective measure known as the Hold Harmless rule. This statutory provision ensures that a Social Security recipient’s net monthly benefit check cannot decrease from one year to the next solely due to Part B increases.
Many seniors mistakenly assume this statute guarantees they will keep their entire 3.6% cost-of-living raise. In reality, the rule only ensures that the Part B hike cannot exceed your dollar raise.
If your 3.6% raise equals $10, a $10 premium hike can legally absorb your entire raise. Your net payment would remain completely flat, giving you an effective cost-of-living increase of zero percent.
Furthermore, federal law explicitly excludes millions of Americans from Hold Harmless protections entirely. New Medicare enrollees who begin their Part B coverage in 2027 receive no protection under the statute.
Retirees who do not have Part B premiums deducted directly from monthly Social Security payments are also excluded. Beneficiaries whose premiums are paid by state Medicaid programs do not fall under the rule either.
Finally, higher-income retirees subject to income-related surcharges cannot rely on Hold Harmless rules. If your earnings exceed federal thresholds, Medicare absorbs as much of your benefit as necessary to cover the surcharge.
IRMAA Surcharges for Higher-Income Retirees
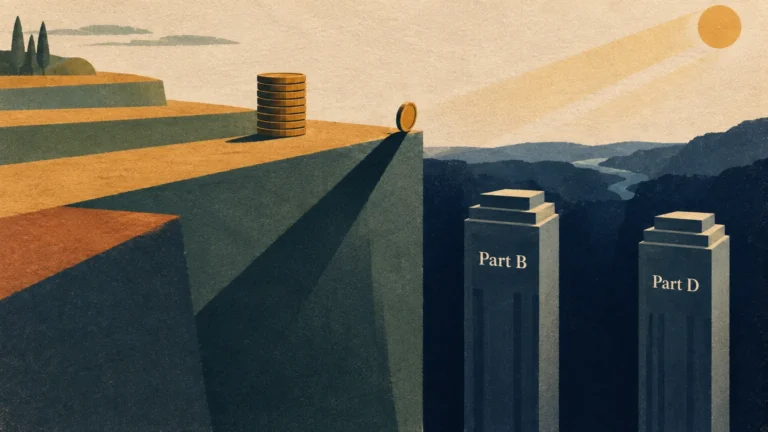
The Income-Related Monthly Adjustment Amount applies an additional surcharge to Medicare Part B and Part D premiums for higher-income individuals. This surcharge creates a sudden financial cliff for unwary retirees.
Federal agencies calculate your 2027 IRMAA tier using your 2025 federal income tax return. If a one-time event inflated your 2025 earnings, your 2027 Medicare premiums will spike sharply.
Selling a home, completing a large Roth conversion, or taking sizable capital gains in 2025 can trigger this penalty. Exceeding an income threshold by a single dollar pushes you into a higher premium tier.
When IRMAA surcharges kick in, they frequently exceed the entire dollar amount of your 3.6% Social Security raise. You might even experience a net decrease in total monthly income despite the nationwide cost-of-living adjustment.