Strategy Pillar 1: Proactive Income and Tax Planning
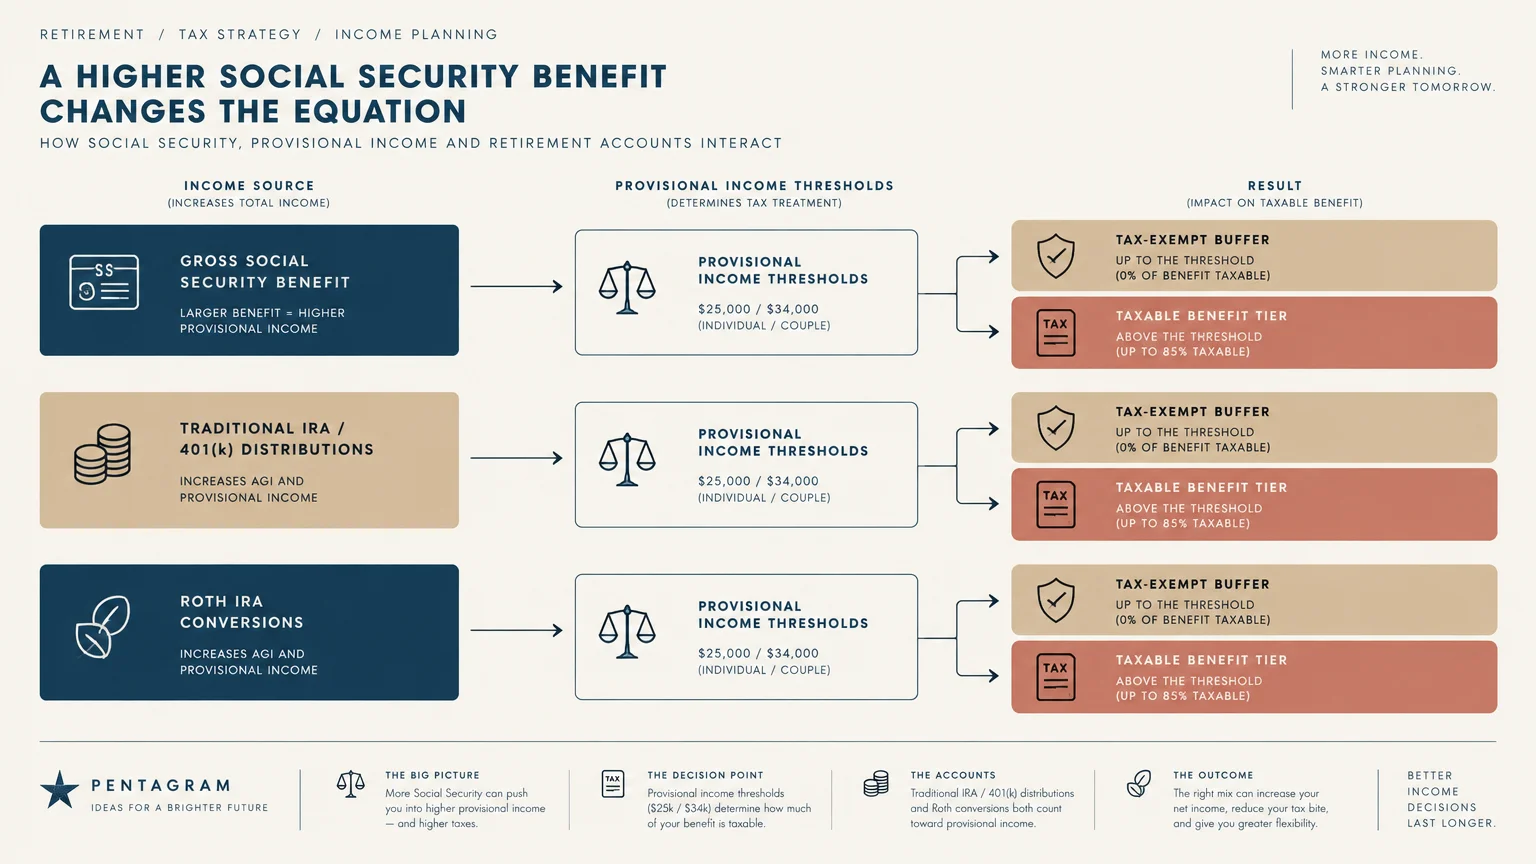
Securing your retirement cash flow requires proactive coordination between your investment withdrawals and Social Security benefits. Thoughtful income structuring helps you retain a higher percentage of your annual raise.
Certified Financial Planner professionals recommend monitoring your combined income annually to minimize tax exposure. Managing distribution timing from taxable, tax-deferred, and tax-free accounts prevents bracket creep.
If you face looming IRMAA surcharges due to required minimum distributions, consider utilizing Qualified Charitable Distributions. Individuals aged 70½ and older can transfer up to statutory annual caps directly from an IRA to an eligible charity.
Qualified Charitable Distributions satisfy your required distribution requirements without adding a single dollar to your Adjusted Gross Income. This simple strategy helps keep your combined income beneath Medicare surcharge thresholds.
Pre-retirees should also evaluate strategic Roth conversions during their lower-income transition years. Converting traditional retirement funds before claiming Social Security reduces required distributions later in life.
If your 3.6% raise pushes you into taxable territory, adjust your federal withholding. Submitting IRS Form W-4V to your local Social Security office prevents an unpleasant tax bill the following April.
Strategy Pillar 2: Healthcare Cost Optimization
Because healthcare premiums represent the primary drain on cost-of-living adjustments, managing medical coverage is vital. Seniors must treat the autumn Medicare Open Enrollment period as an annual financial checkup.
Review your annual Notice of Change from your Medicare Advantage or Part D prescription drug insurer. Plans alter provider networks, medication copayments, and drug tiers every single calendar year.
A medication you take could shift to a higher pricing tier in 2027. Switching to an alternative plan during enrollment can easily save you far more than the $6.60 projected monthly Part B increase.
Explore whether you qualify for a Medicare Savings Program through your state Medicaid agency. These state-administered programs pay Part B premiums for eligible individuals with limited monthly income and resources.
If approved for a Medicare Savings Program, your state covers the monthly Part B deduction completely. This coverage allows you to keep your entire 3.6% cost-of-living adjustment in your monthly benefit check.
Additionally, take full advantage of no-cost preventive care services covered under Medicare Part B. Annual wellness visits, routine screenings, and immunizations help you identify health issues before they become costly medical emergencies.
Strategy Pillar 3: Purposeful Lifestyle and Budget Design
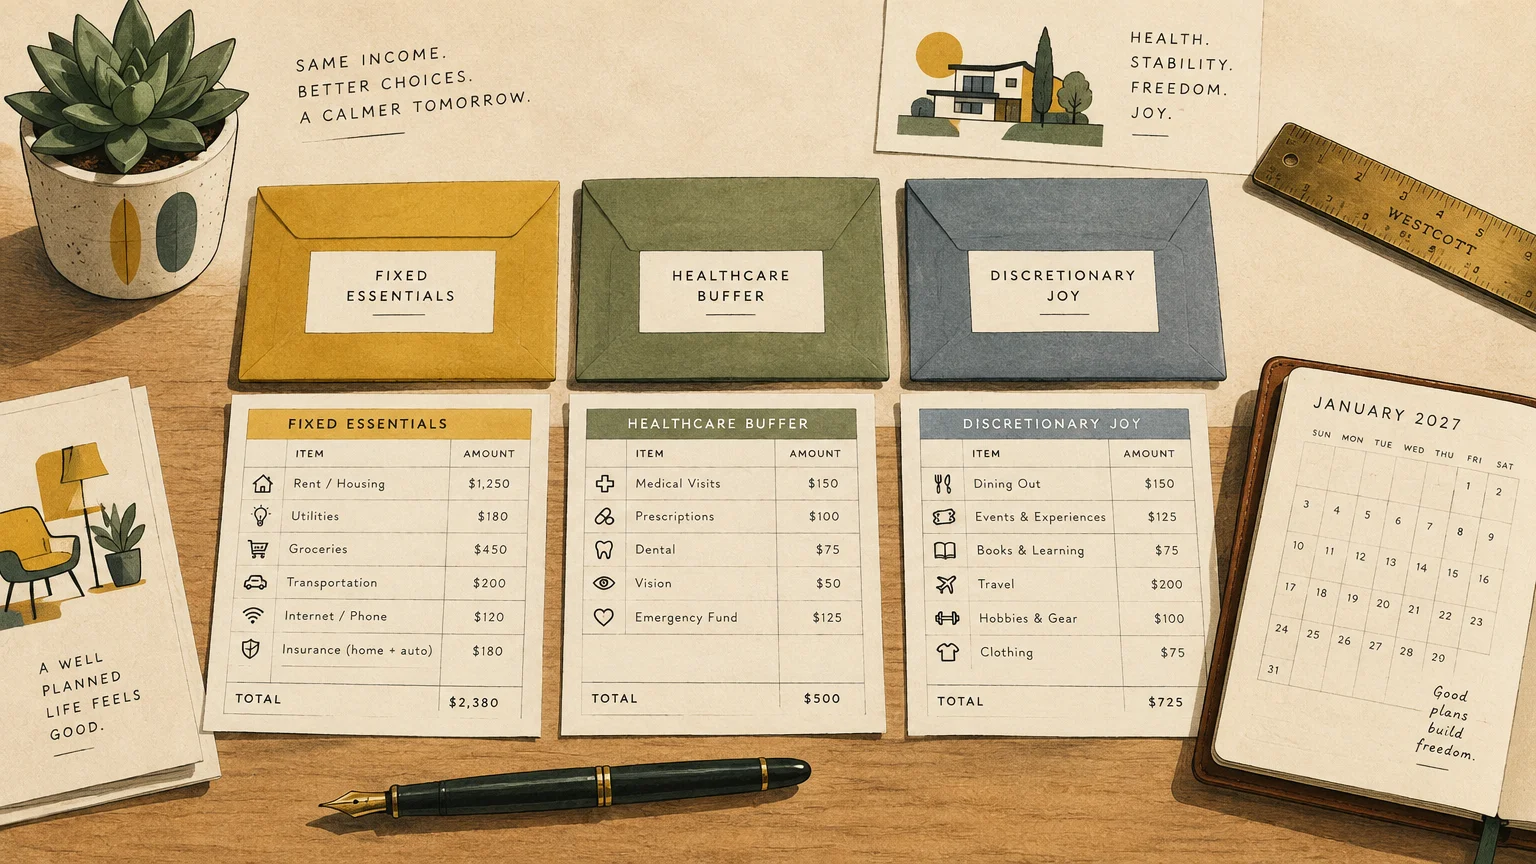
Relying solely on federal benefit adjustments to manage cost increases often proves frustrating. Older Americans achieve greater financial stability by actively adjusting household spending routines.
Senior-specific inflation frequently outpaces the headline Consumer Price Index used by federal agencies. The Bureau of Labor Statistics tracks specialized inflation data showing that medical and housing costs weigh heavily on older households.
Perform an annual budget audit each November once the Social Security Administration announces the COLA rate. Allocate your anticipated $75 average monthly increase toward high-priority expenses or emergency cash reserves.
Contact utility companies to ask about senior discount programs or budget billing arrangements. Many electric, gas, and water utilities offer reduced rates to older adults living on fixed incomes.
Investigate local property tax exemptions designed for older homeowners through your county assessor. Many municipalities freeze assessed home values or provide property tax credits once homeowners reach age 65.
Maintaining strong social connections and staying physically active also support long-term financial health. Community senior centers offer accessible fitness programs, nutritious meals, and social activities at little to no cost.
Gerontologists emphasize that active lifestyle habits reduce long-term dependency on paid care services. Investing time in your physical and mental health protects your retirement savings far better than any statutory COLA.
Safeguards Against Scams and Costly Administrative Traps
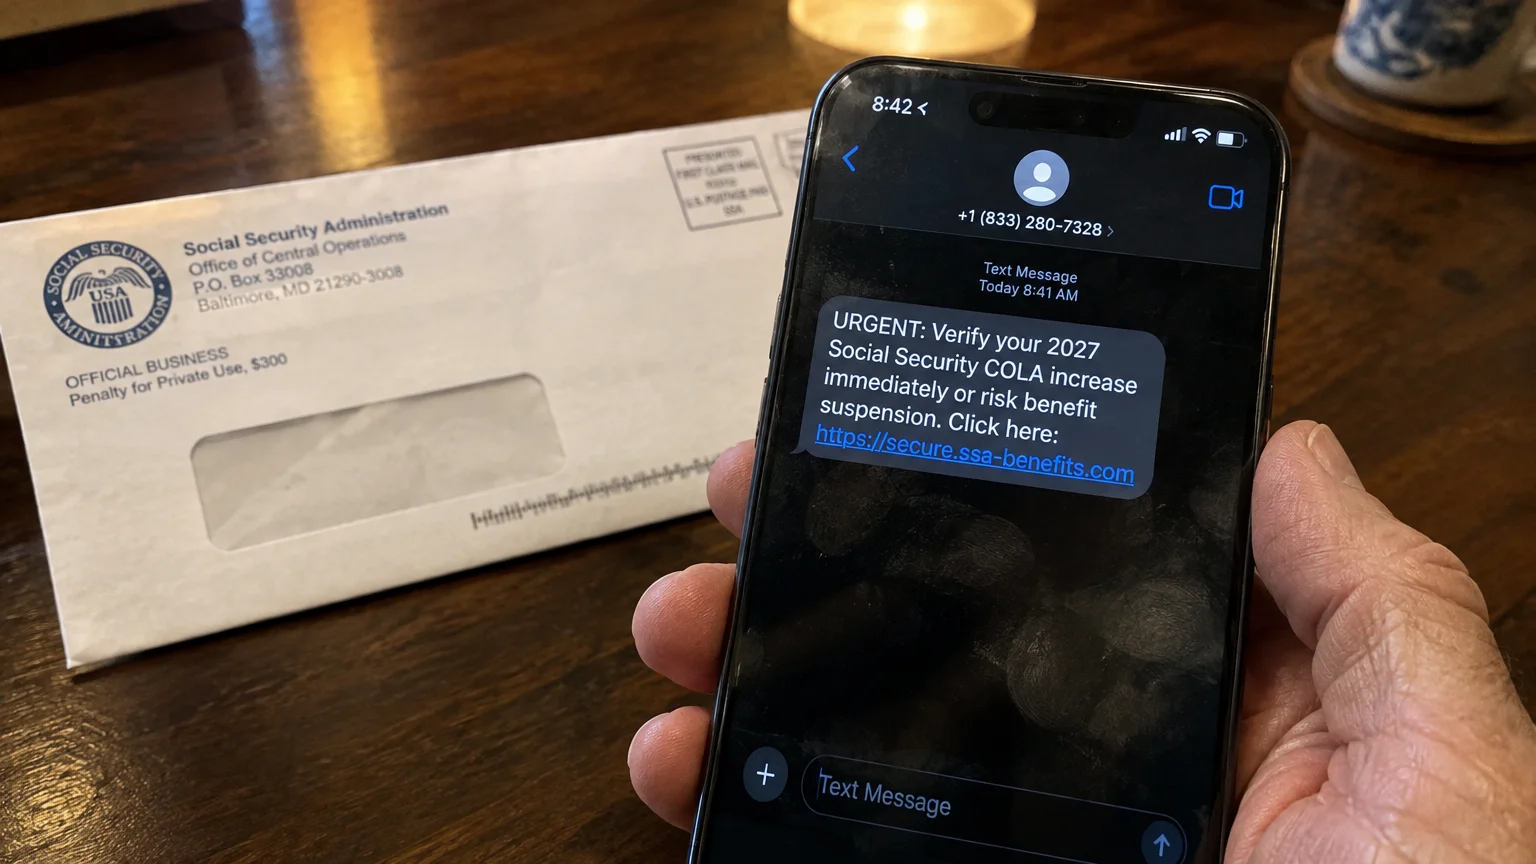
Federal benefit adjustments inevitably generate a wave of fraudulent schemes targeting older adults. Criminals exploit news coverage surrounding the 3.6% COLA to steal personal information from unsuspecting beneficiaries.
Scammers contact seniors via phone, text message, or email claiming you must “activate” or “apply for” your 2027 raise. They demand your Social Security number, banking details, or an upfront processing fee.
The Social Security Administration never charges fees or requires personal verification to apply an official cost-of-living increase. Your 3.6% adjustment occurs completely automatically under federal law.
Never share personal credentials or banking numbers with unverified callers. If you receive a suspicious message regarding your benefits, report the incident immediately to federal authorities.
Protect your online *my Social Security* portal by establishing strong login credentials and multi-factor authentication. Regularly reviewing your account ensures no unauthorized individuals alter your direct deposit routing numbers.
For additional consumer protection tips and retirement community guidance, consult trusted resources such as AARP. Staying informed protects your hard-earned benefits from deceptive predatory practices.
Frequently Asked Questions About the 2027 COLA
Will higher Medicare Part B premiums wipe out my entire 3.6% raise?
For most retirees, the projected $6.60 Part B premium increase will only absorb a portion of the monthly raise. Beneficiaries receiving the average $75 monthly increase will still see net cash flow improve.
However, if your monthly benefit is very small, a $6.60 deduction consumes a much larger percentage of your raise. The Hold Harmless rule prevents your net check from dropping, but it can reduce your net gain to zero.
Can I appeal an IRMAA surcharge if my income dropped after 2025?
Yes, you can request an initial determination review by filing Form SSA-44 with the Social Security Administration. The agency grants appeals if your income dropped due to recognized life-changing events.
Qualifying events include retirement, work reduction, marriage, divorce, or the death of a spouse. You must provide documentation, such as tax transcripts or employer statements, proving your reduced financial circumstances.
If Social Security withholds benefits under the earnings test, is that money gone forever?
No, benefit withholdings under the Retirement Earnings Test are not permanent financial penalties. Once you reach Full Retirement Age, the agency recalculates your primary insurance amount upward.
This statutory adjustment permanently increases your monthly check to compensate for benefits withheld while working. Over time, you recover the withheld funds through higher baseline monthly payments.
What happens if I miss the November 18, 2026 digital notice deadline?
Missing the November 18 digital deadline does not affect your benefit payment or your cost-of-living adjustment. It simply means the agency will send your annual COLA notice through the U.S. Postal Service.
The agency mails paper notices throughout December 2026 to your registered address. You can still access digital copies inside your online portal once the initial batch processing finishes.
Take Action in the Next 48 Hours
Do not wait until January to find out how the 2027 cost-of-living adjustment affects your monthly budget. Taking one decisive step over the next two days provides clarity and protects your bottom line.
Log into your personal *my Social Security* account before the November 18, 2026 paperless deadline. Setting your communication preferences now ensures you receive your personalized rate notice at the earliest possible date.
Next, visit the Medicare plan finder tool to review your prescription drug coverage before open enrollment closes on December 7. Comparing available plans takes less than an hour and frequently saves hundreds of dollars annually.
Finally, examine your 2025 tax filings to anticipate any potential IRMAA surcharges or combined income tax triggers. Being proactive puts you in control of your financial future, ensuring you keep every dollar you deserve.