You can slash thousands of dollars off your annual housing expenses through underutilized state property tax relief programs. Rising residential assessments continue to squeeze fixed budgets across the United States.
Recent legislative expansions create immediate financial protection for older homeowners who know where to look. These statutory breaks keep your home affordable without forcing you to downsize.
Discover five overlooked exemptions, credits, and deferrals that lower your bill in 2026. Claiming these benefits shields your hard-earned nest egg and strengthens your long-term independence.
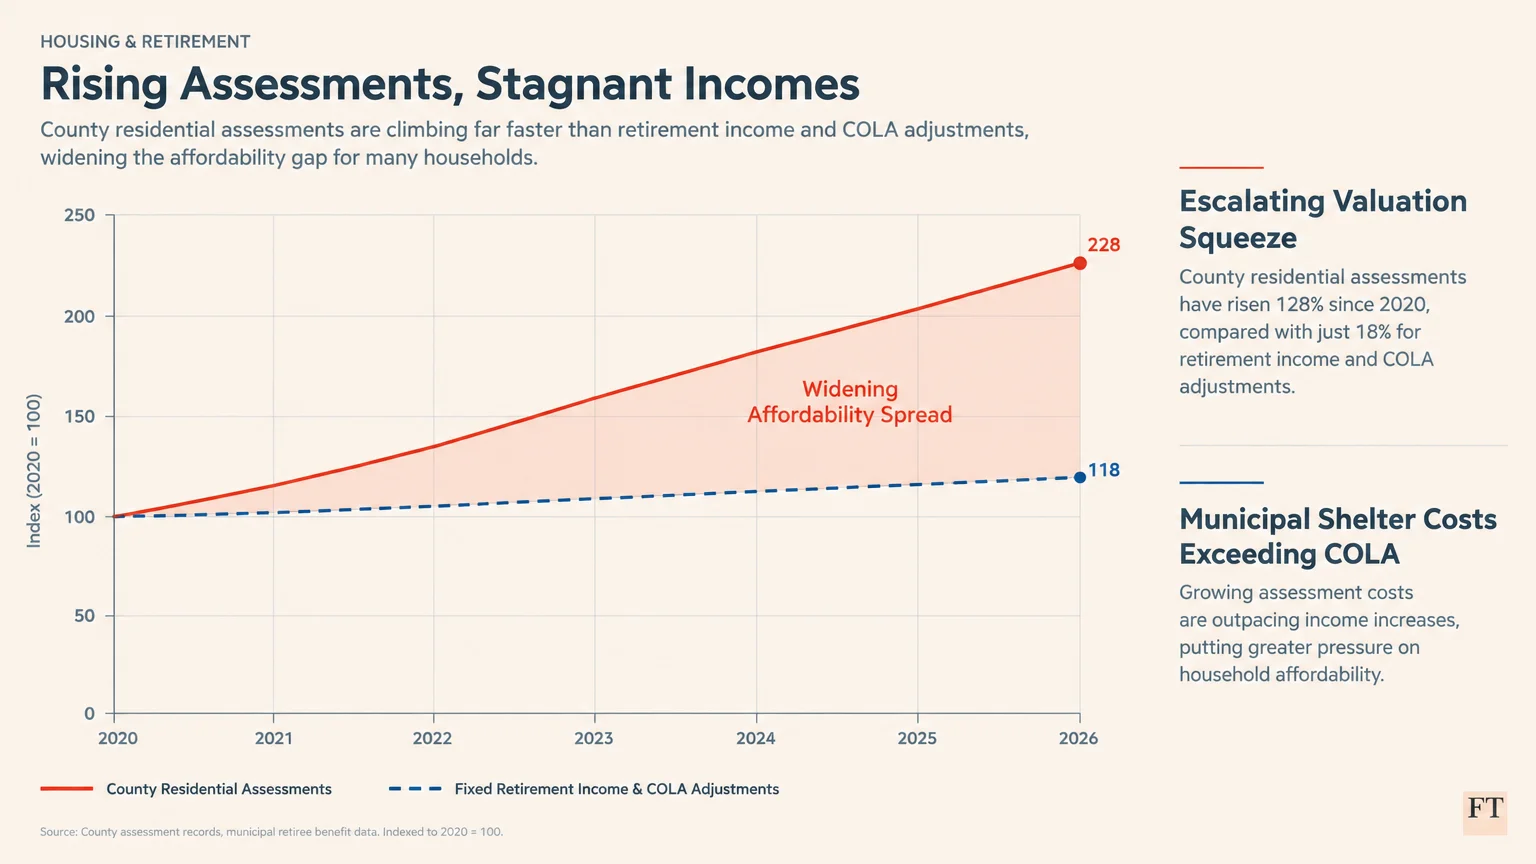
Understanding Rising Assessments in 2026
Homeownership represents the primary financial anchor for most American retirees. Yet escalating county valuations have transformed paid-off residences into substantial ongoing tax liabilities.
Reports from the Bureau of Labor Statistics show municipal shelter costs rising faster than annual Social Security adjustments. This widening spread creates sharp financial stress for retirees living on fixed incomes.
The AARP notes that escalating property taxes remain a leading driver of housing insecurity for seniors. Defending your home requires identifying and claiming state and local statutory programs.
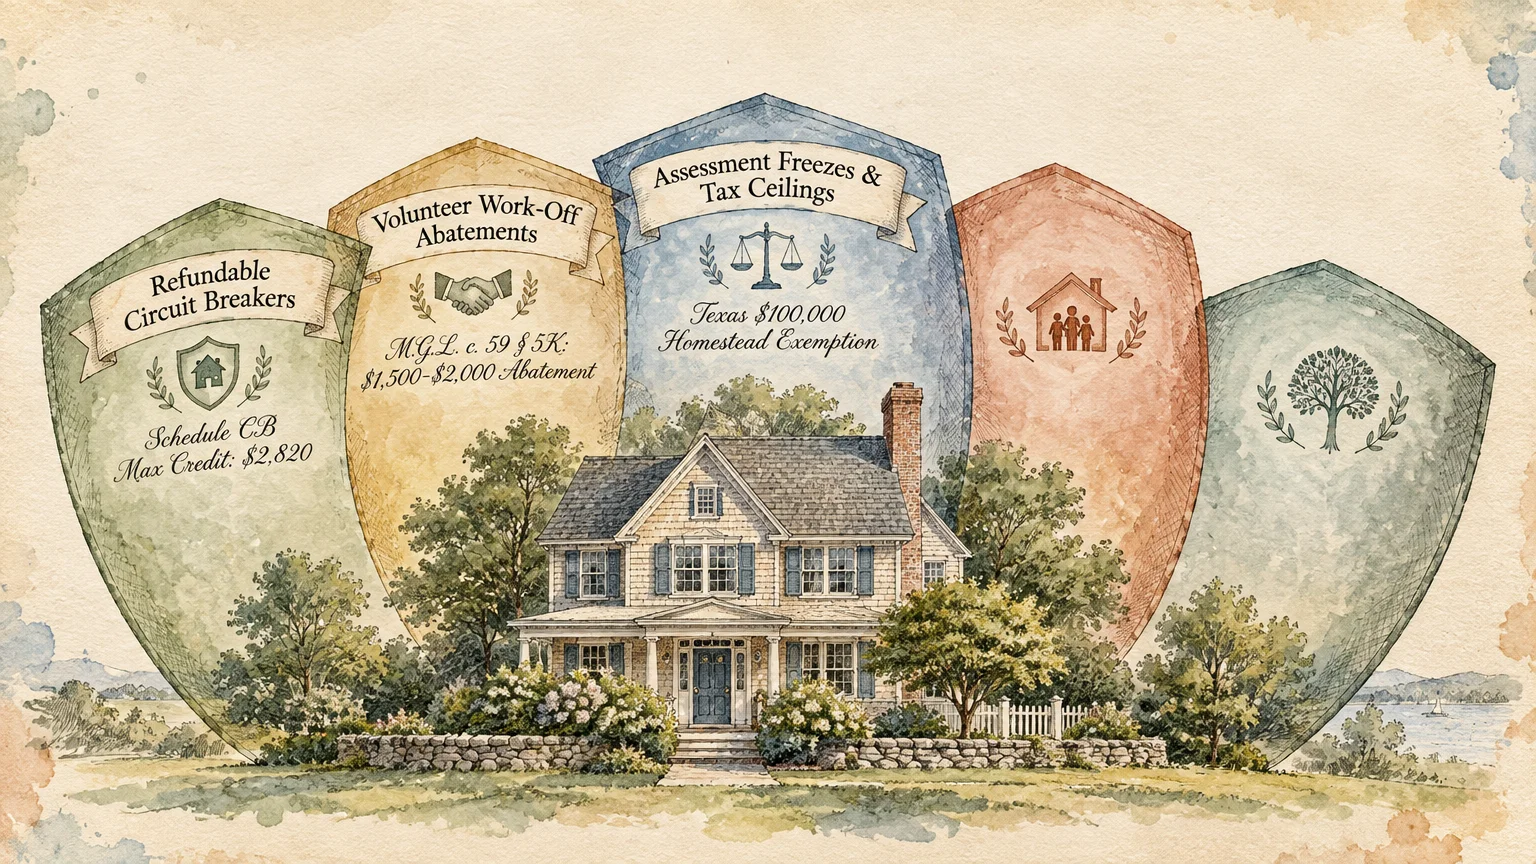
Five Overlooked Senior Property Tax Breaks
1. Refundable State Circuit Breaker Credits
Circuit breaker programs halt real estate tax bills before they overwhelm your annual retirement budget. When your property taxes exceed a designated percentage of household income, the state offsets the excess.
Massachusetts provides a leading model through its Schedule CB tax credit. Eligible homeowners and renters aged 65 and older can claim a refundable credit worth up to $2,820 this year.
You qualify if your real estate tax and half your water/sewer bills exceed 10% of total income. The state caps eligible home valuations at $1,298,000 for this relief.
Because Schedule CB is refundable, you receive a direct payment even if you owe no state taxes. Multiple other states offer comparable circuit breaker relief on state income returns.
2. Municipal Volunteer Work-Off Abatements
Municipalities frequently allow senior homeowners to trade volunteer service for direct reductions on their real estate taxes. These local initiatives help towns fill community roles while providing meaningful tax abatements.
Under Massachusetts General Laws Chapter 59 Section 5K, participating communities allow residents aged 60 and older to earn property tax reductions. Qualifying participants can earn abatements up to $1,500 to $2,000 annually.
Participants complete clerical or support projects in public libraries, municipal archives, senior centers, or local parks. The municipality calculates earned credits using local minimum wage rates and credits the sum directly against your bill.
Towns in Colorado, New Hampshire, and Pennsylvania operate comparable senior volunteer abatement programs. Contact your local tax assessor or town clerk to explore available volunteer tax credit positions.
3. County Assessment Freezes and School Ceilings
Assessment freezes protect seniors from market-driven valuation surges that produce sudden property tax hikes. These statutes lock in your home value or tax levy at a fixed baseline year.
Missouri enacted powerful protection under Senate Bill 190 and Senate Bill 756 for homeowners aged 62 and older. Multiple counties, including St. Louis and Jackson, now actively freeze county property taxes on primary residences.
Texas combines a $100,000 homestead exemption with a mandatory $10,000 senior exemption for school taxes. Texas law also imposes an absolute constitutional tax ceiling on school district taxes for homeowners aged 65 and older.
This constitutional ceiling locks the dollar amount of your school taxes for as long as you occupy the home. Even if your market valuation doubles over time, your school tax levy remains permanently frozen.
4. Expanded Medical and Auxiliary Deductions
Many senior tax relief programs enforce strict income caps that exclude households earning modest pension income. Emerging statutory updates in 2026 resolve this barrier by establishing generous allowable deductions before calculating eligibility.
Washington State expanded senior property tax relief under ESSB 6162, taking effect June 11, 2026. The statute establishes an automatic standard medical expense deduction of $7,500 per applicant when calculating Combined Disposable Income.
Married couples filing jointly claim a combined $15,000 standard medical deduction against their qualifying income. The law also permits an allowable deduction of up to $6,000 for rental income generated from auxiliary dwelling spaces.
These deductions allow thousands of middle-income seniors to qualify for complete or partial property tax exemptions. Documenting qualified medical and housing expenses helps bring your net income under strict statutory thresholds.
5. State-Backed Property Tax Deferral Programs
Senior property tax deferral programs allow cash-constrained retirees to postpone real estate tax payments indefinitely. The state treasury pays your county tax collector directly, preventing delinquent tax sales.
The California State Controller’s Office manages the Property Tax Postponement program for seniors aged 62 and older meeting equity and income standards. Oregon and Washington offer similar state-backed postponement options.
The state secures deferred payments by placing a lien against your residential property at modest statutory interest rates. The deferred balance becomes due only when you sell the property, refinance, or pass away.
Deferrals provide an essential financial lifeline for older homeowners experiencing temporary or chronic cash shortages. They allow you to stay in your home without the fear of municipal tax foreclosure.
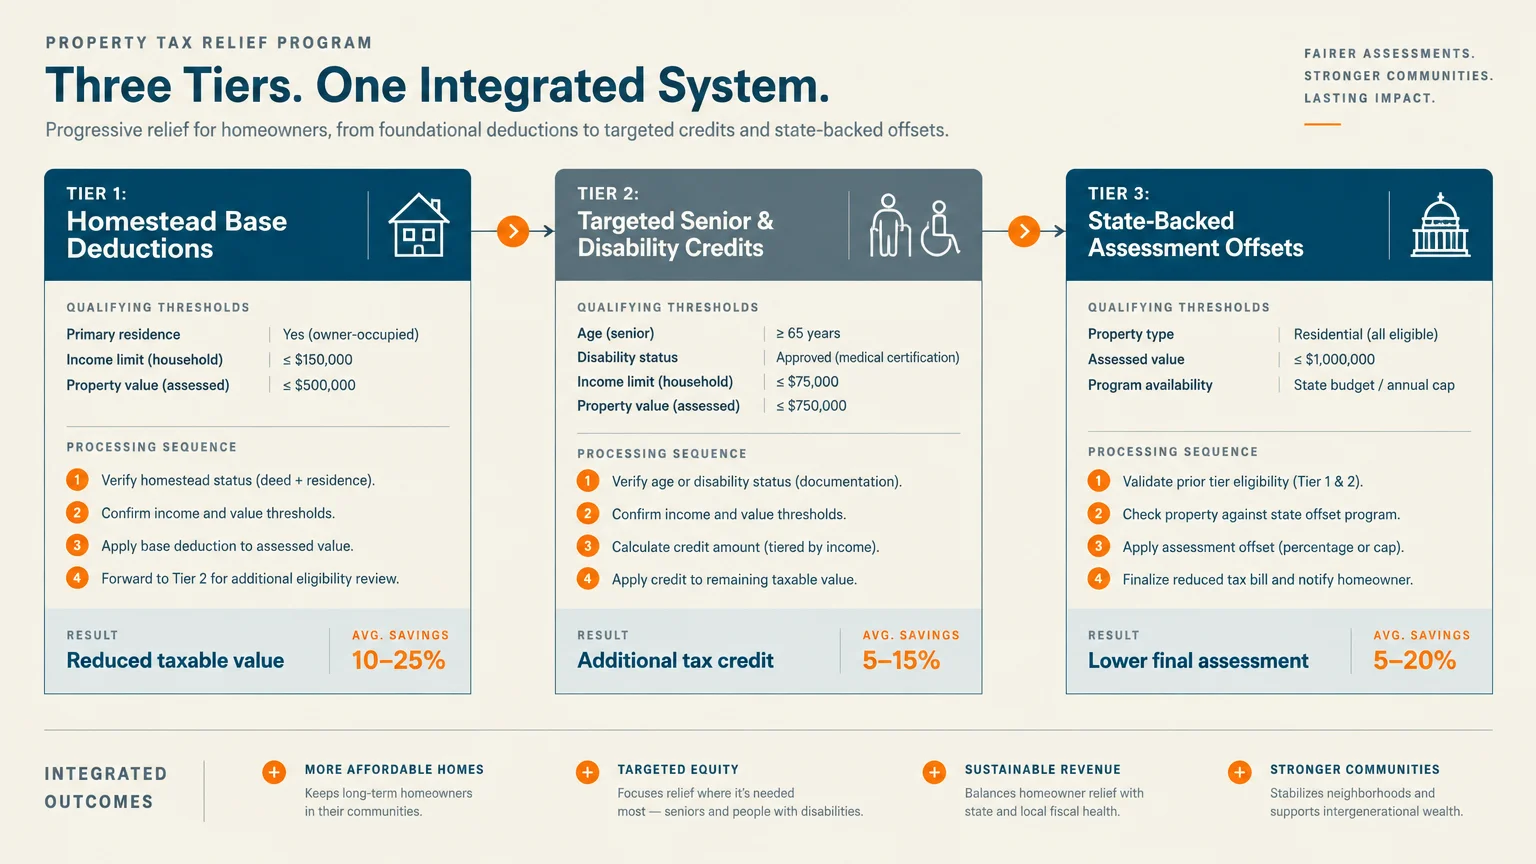
Integrated Relief Models: The New Jersey Benchmark
New Jersey launched the Stay NJ initiative to dramatically ease property tax burdens on older homeowners. The program integrates with existing ANCHOR and Senior Freeze programs to deliver coordinated tax relief.
Stay NJ cuts property taxes by up to 50% for qualifying homeowners aged 65 and older. The state caps this annual relief at up to $6,500 per eligible household.
State officials streamlined relief by consolidating applications into a single unified form called the PAS-1. Eligible homeowners must file their unified application before the November 2, 2026 deadline.
Integrated programs eliminate redundant paperwork and ensure eligible seniors receive the maximum benefits allowed by law. More states are considering unified applications to boost participation in senior assistance programs.
Strategic Pillars for Housing Wealth and Preservation
Pillar 1: Income Planning and Bracket Optimization
Maximizing property tax relief requires strategic coordination of your taxable withdrawals and adjusted gross income. Taking an uncoordinated lump-sum withdrawal from your retirement account can push your income over strict statutory ceilings.
You should review distribution strategies outlined by the Internal Revenue Service before liquidating tax-deferred assets. Strategic Roth conversions executed prior to age 65 can keep your future disposable income safely below local exemption thresholds.
Partnering with a fiduciary advisor helps balance portfolio withdrawals against potential property tax abatements. Protecting an annual tax credit worth several thousand dollars often delivers superior financial value compared to aggressive distributions.
Pillar 2: Lifestyle Design and Aging in Place
Lowering your housing expenses frees up discretionary cash to adapt your home for long-term mobility needs. Investing tax savings into walk-in showers, reinforced handrails, and zero-step entries allows you to age in place safely.
Participating in municipal tax work-off initiatives fosters active civic engagement and combats social isolation. Serving in public offices keeps you connected with local neighbors and civic leaders across generations.
Remaining in your familiar neighborhood preserves vital proximity to trusted medical providers, social networks, and community amenities. Housing affordability serves as the foundation for physical independence and purposeful retirement living.
Pillar 3: Health, Wellness, and Expense Integration
Out-of-pocket medical bills represent a substantial financial drain for older households. However, integrating health accounting with your property tax filings transforms these expenses into valuable exemption deductions.
Reviewing guidance from Medicare helps you track qualified healthcare expenses, including copays, dental work, and supplemental insurance premiums. Several state exemption programs deduct these certified health costs from gross household earnings.
Maintaining thorough records of your annual healthcare expenses ensures you can document all allowable deductions. Every documented medical dollar reduces your combined disposable income, increasing your odds of qualifying for relief.
Expert Perspectives on Housing Security
Certified Financial Planner professionals stress that real estate taxes represent an uncontrollable expense without active intervention. Lowering housing overhead shields your investment portfolio from accelerated withdrawals during volatile market downturns.
Gerontologists note that the emotional stability of secure housing directly correlates with improved physical vitality and mental health. Relieving the stress of looming tax liens enables retirees to focus on healthy lifestyle habits.
Retirees who take the initiative to consult local assessors often uncover relief programs rarely advertised in mainstream media. Asking targeted questions at the town hall can unlock thousands in recurring annual savings.
Risks, Benefit Cliffs, and Common Traps
Deceptive commercial firms frequently market fee-based filing services to older homeowners for public property tax programs. Remember that your local county tax assessor provides all application paperwork and assistance completely free of charge.
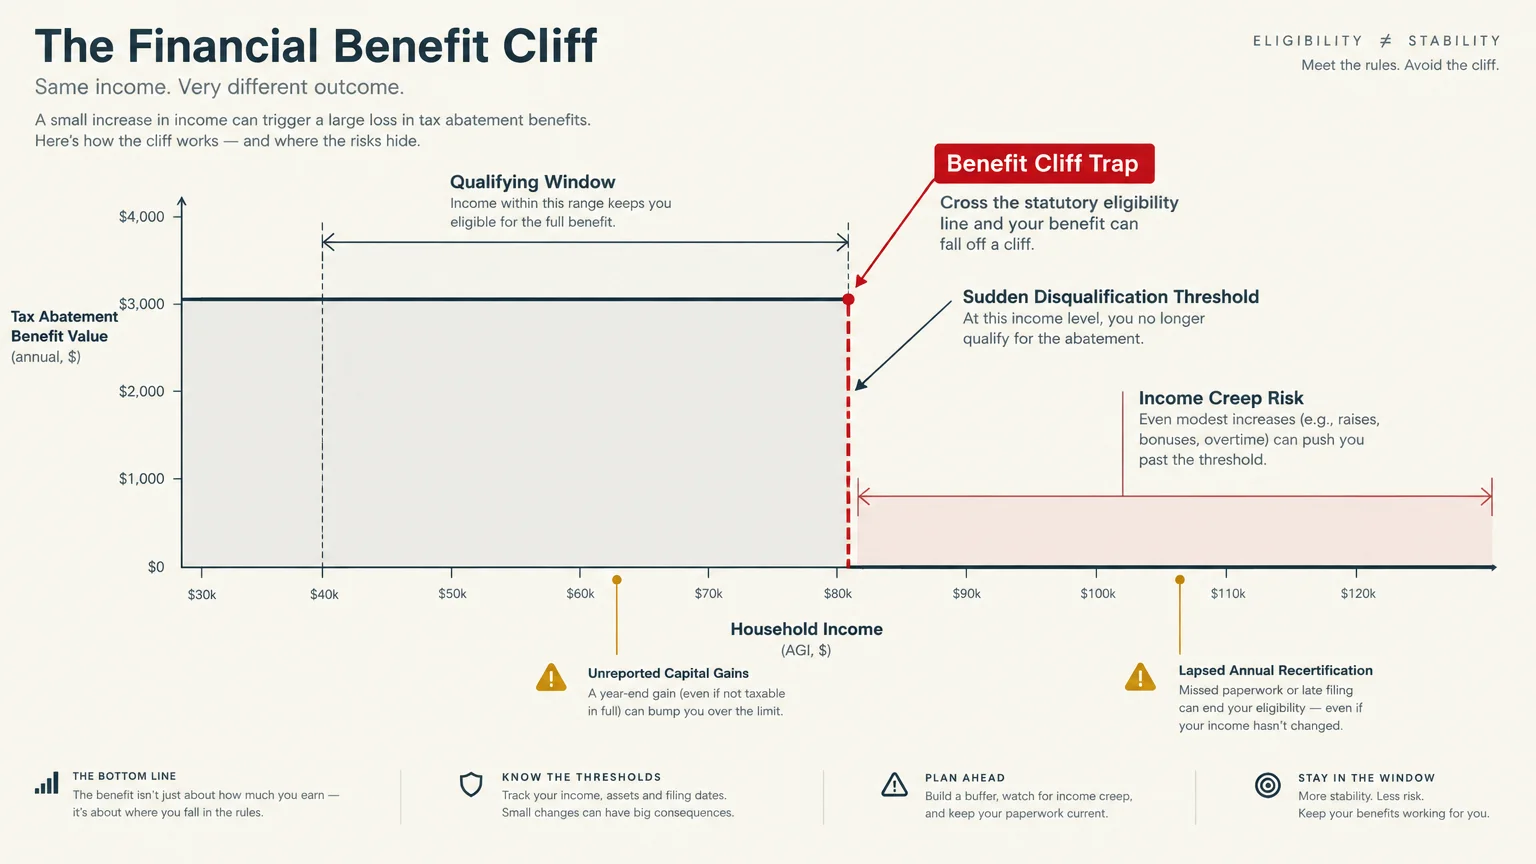
Beware of benefit cliffs where exceeding statutory income caps by even a few dollars triggers a complete forfeiture of relief. Carefully forecasting your annual retirement earnings protects you from accidentally crossing these thresholds.
Property tax deferral programs require transparent communication with your designated estate beneficiaries and legal counsel. Because deferred taxes create a statutory lien against your property, your estate must resolve the balance after your death.
Make sure you review interest terms and statutory conditions before enrolling in any tax postponement system. Discussing deferral terms with an elder law attorney ensures your heirs encounter no unexpected financial burdens.
Frequently Asked Questions
Does a property tax freeze reduce my home market value?
An assessment freeze or tax ceiling does not decrease your property’s actual market valuation. The freeze merely limits the taxable assessed value that county officials use to compute your annual tax bill.
Your home equity continues to grow alongside broader market conditions and neighborhood property trends. When you eventually choose to sell your residence, you capture the full market price from prospective buyers.
Can I combine multiple senior property tax relief programs?
In many jurisdictions, homeowners can layer multiple programs to achieve maximum cumulative property tax savings. For instance, Texas homeowners routinely combine general homestead exemptions, senior exemptions, and school district tax ceilings.
Other states permit you to claim state circuit breaker tax credits while receiving local municipal abatements. Consult your county assessor or municipal clerk to confirm program compatibility in your specific area.
Are municipal volunteer tax credits subject to taxation?
The federal government generally treats municipal property tax abatements earned through volunteer work as taxable wages. However, several states provide statutory exemptions that protect these modest credits from state income taxation.
Your municipality will provide an informational tax statement detailing the abatement amount applied to your property bill. Check with your tax professional to confirm the specific reporting rules for your state and locality.
What occurs with deferred taxes when a homeowner passes away?
Postponed property taxes become due and payable once the homeowner passes away or permanently transfers the property title. Most state programs provide designated heirs with a reasonable grace period to satisfy the accrued balance.
Heirs can clear the statutory lien using estate cash, mortgage refinancing, or proceeds from selling the home. All remaining equity belongs entirely to your estate once the state tax lien is fully settled.
Take Action Within the Next 48 Hours
Lowering your property taxes does not require months of exhausting administrative struggles or complex legal filings. You can initiate meaningful tax relief by taking a single decisive step over the next two days.
Locate your latest property tax assessment bill and highlight your parcel identification number. Visit your county tax assessor website to download their senior exemption forms and confirm upcoming application deadlines.
Contact your local municipal assessor or council on aging to ask about active volunteer work-off programs. Taking ownership of your property tax strategy today preserves your home, your wealth, and your peace of mind.