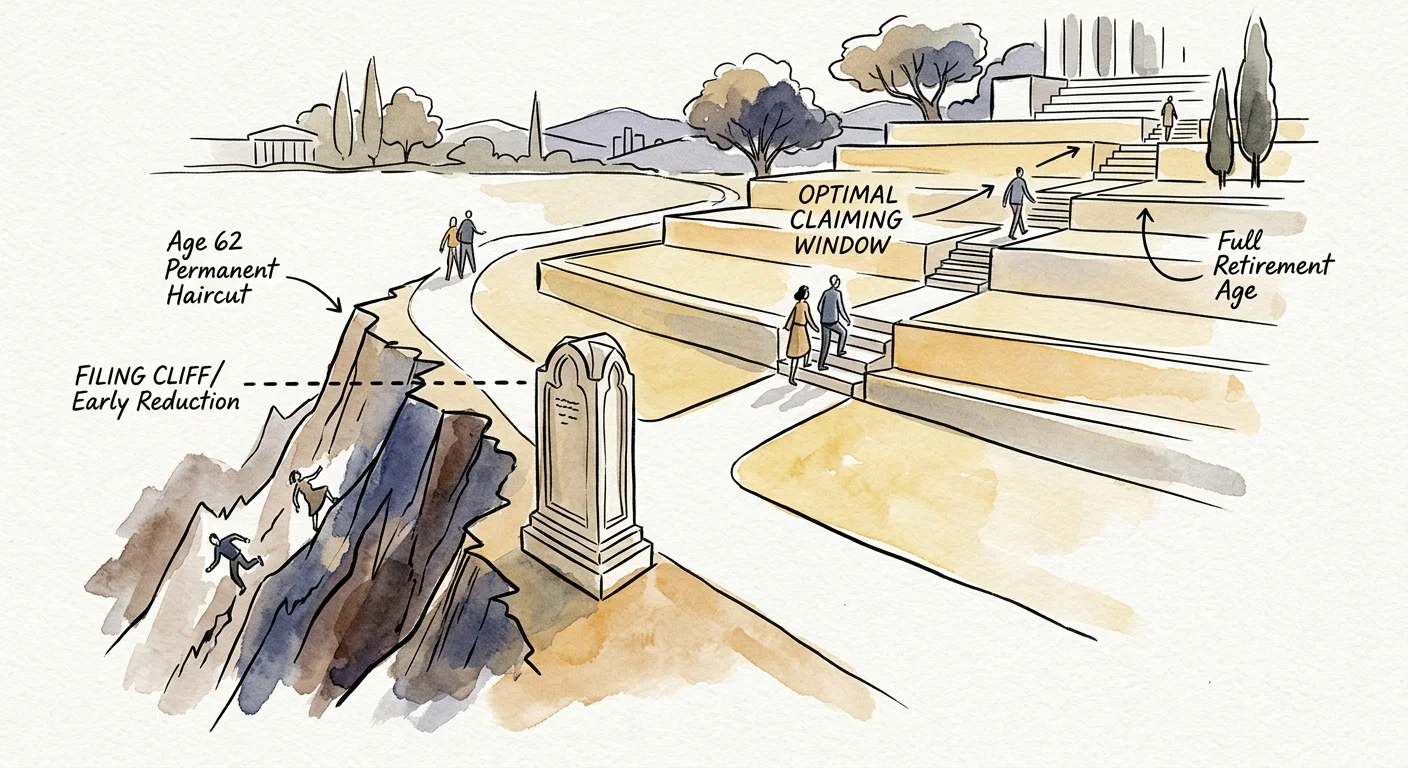
Benefit Cliffs and Filing Traps
Filing for ex-spousal benefits before reaching Full Retirement Age results in a permanent payout reduction. Furthermore, if you claim benefits before your FRA while continuing to work, the Social Security earnings test reduces your check if earnings exceed federal thresholds. Data from the Bureau of Labor Statistics highlights that many older adults maintain flexible employment, making earnings limits a key consideration for working retirees.
Another common pitfall involves missing documentation. Government offices require original marriage certificates, divorce decrees, and your ex-spouse’s identifying details to process claims. Gathering these documents early prevents administrative delays.
Yes, I have been married multiple times but my first marriage was of 23 years and then my second one is a 15 years and my first marriage. She’s already collecting Social Security and I will be 62 in October but they said I cannot collect on my first marriage. Thought I would have to be divorced from my second husband to collect off of my first husband, even though my husband now is 63 and he will not collect Social Security until he is 65 but I should be able to collect I think in my own mind from my first husband at 62 because he is 66 and he’s already collecting.
I am not an expert on Social Security just from life experiences and what I read, but I think once you marry after divorce you lose the ability to collect on that person, that is what I think is true. What about collection on your own Soc. Sec. until your husband retires, then it will be half of his, and then you will lose yours if his is more.
You can collect on a previous spouse ssn if you wait to remarry after 60. Then you can start collecting on your previous spouse’s ssn at 60 with no penalties. But you have to wait to remarry after 60 years of age.
I received this info from my financial advisor at Fidelity while auditing my financial health & if I’m on a right path to retire at 62 years old.