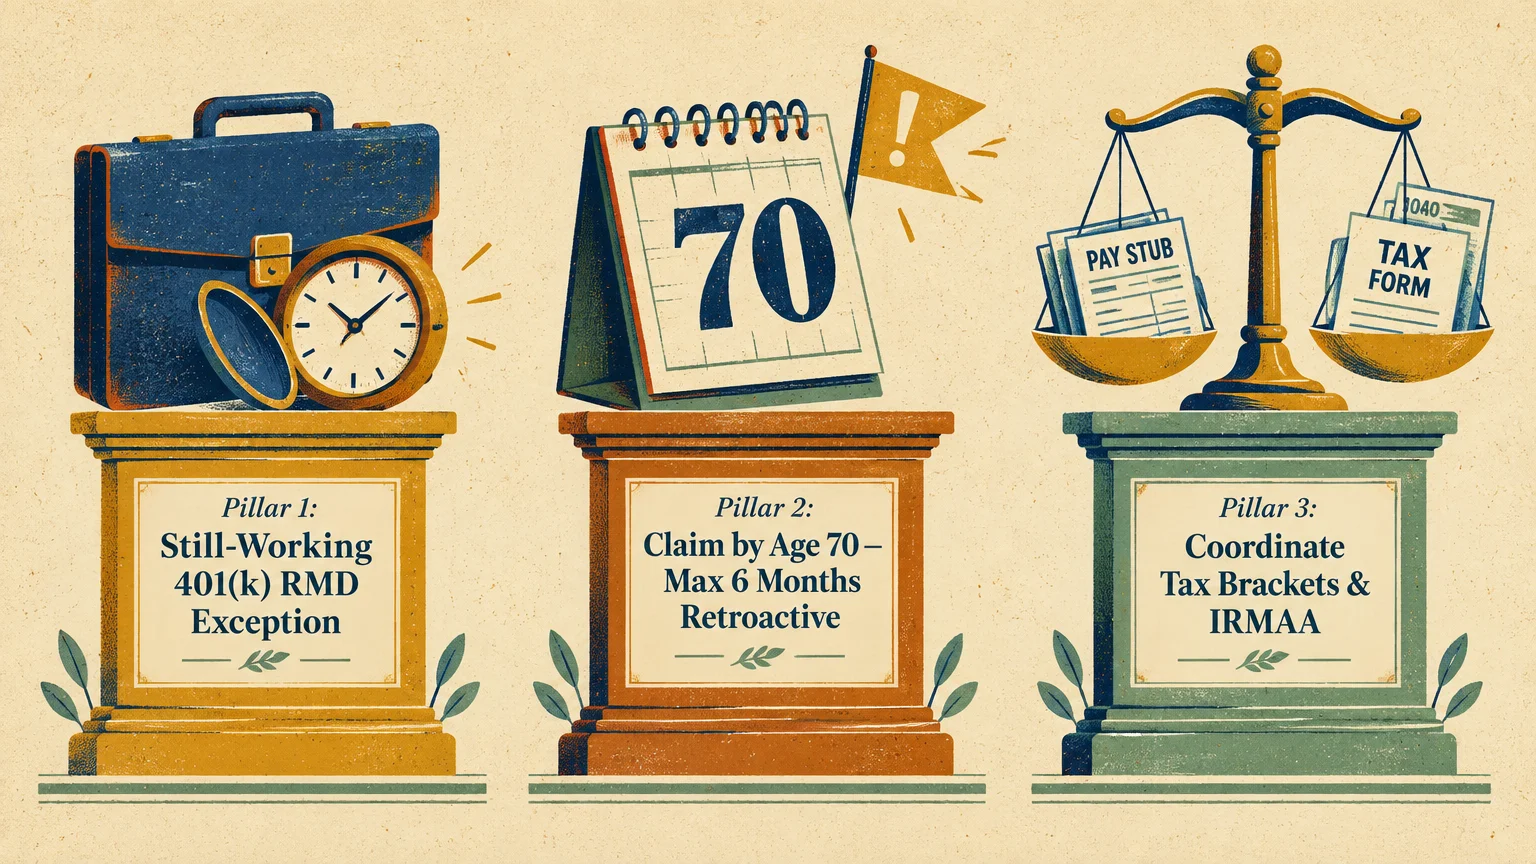
Three Strategic Pillars for Working Beyond 75
Balancing a career in your late seventies requires purposeful coordination between your financial portfolio, daily lifestyle, and physical vitality.
Focusing on three core pillars allows you to maximize your workplace satisfaction while protecting your hard-earned benefits.
Pillar 1: Proactive Income and Tax Planning
Coordinating your paychecks with required retirement withdrawals prevents unexpected tax surges at the end of the year.
Certified financial planner Marcus Vance advises clients past 75 to explore qualified charitable distributions from traditional individual retirement accounts.
Directing your mandatory account distributions directly to qualified charities satisfies IRS withdrawal mandates without swelling your adjusted gross income.
You should also verify whether your employer sponsors a workplace retirement savings plan that accepts contributions from active older workers.
Contributing pre-tax salary to an active employer plan lowers your adjusted gross income and helps preserve your benefit payouts.
Pillar 2: Lifestyle Design and Workplace Flexibility
Designing a flexible work routine helps you maintain career satisfaction without compromising your daily independence or physical well-being.
Gerontologist Dr. Elena Ramirez notes that flexible schedules support cognitive vitality while preventing fatigue among older professionals.
You can discuss converting traditional full-time obligations into part-time consulting contracts or seasonal project assignments with your employer.
Negotiating remote work options eliminates taxing physical commutes and lets you customize your desk setup for ergonomic comfort.
Establishing clear professional boundaries protects your time for family commitments, physical activity, and community hobbies.
Pillar 3: Protecting Your Health and Medicare Coverage
Protecting your health requires navigating the intersection between employer-provided group health insurance and your personal Medicare benefits.
Check guidelines from Medicare to verify whether your workplace policy serves as your primary or secondary insurance.
If your company employs fewer than 20 workers, Medicare acts as primary payer, making Part B enrollment essential to prevent coverage gaps.
Prioritize regular hearing and vision screenings to ensure you can perform your workplace responsibilities safely and comfortably.
Incorporate scheduled walking breaks and gentle stretching into your daily workday to sustain joint mobility and cardiovascular health.
Will my Medicare Social Security check increase at the age of 75?
I paid SS out of my social security benifits and my job was taking money out for SS.
Why am i not receiving more of my money back if i was paying into my SS 2 different ways.
I dont evening receive $1500 after deductions
Diane Irving
I have been working since I started my Social Security. I am now 80 years old and plan to stop working next year 2027. I am sure I have surpassed some lower years of income, will I start receiving more on my monthly payment and do I have make a appointment with Social Security for that to happen?
They should have been recalculating as the years have been passing by contact them immediately
My name is Harvey Liles, I have been drowning early retirement I think starting at 62 I’ve been penalize please over look my spelling, a couple of times for making to much and with the new enrollment I have to give up the,$170.00 just so I can get some dental insurance which even network doesn’t really work help I can’t get all the other benefits you hear them talking about because I am 70 and have insurance with the company I work from could you explain why I can’t get the help I need ???
I am 65 years old about to turn 66 in 3 more months but in why is so hard for seniors to get the correct benefits, undefeated benefits it’s so complicated. They are making everything so complicated about Medicare advantage and supplement, they be advising on television about your social security check about now things should be getting in benefits, my social security check be every month 1,011 that’s my rent, but they say if your check is less than that you can receive all benefits to help pay bills and groceries, but it’s hard getting through to them, I am a type 2 diabetes with kidney and thyroids with a heart monitor on high blood pressure problem with no help, it is so hard for seniors to get the right help they are making everything so complicated my rent is 1,023 and social security check be 1,011 but I am so thankful by the grace of God. These calls every day all day long trying to change your insurance, talking about how they can change your benefits to get you more but they have to check your zip code then they tell you, you not qualified what kind of sense does that makes, zip codes keep seniors from getting benefits help that’s sad. AS WE ARE SO THANKFUL! JESUS