2. Taking Spousal Benefits Early at Age 62
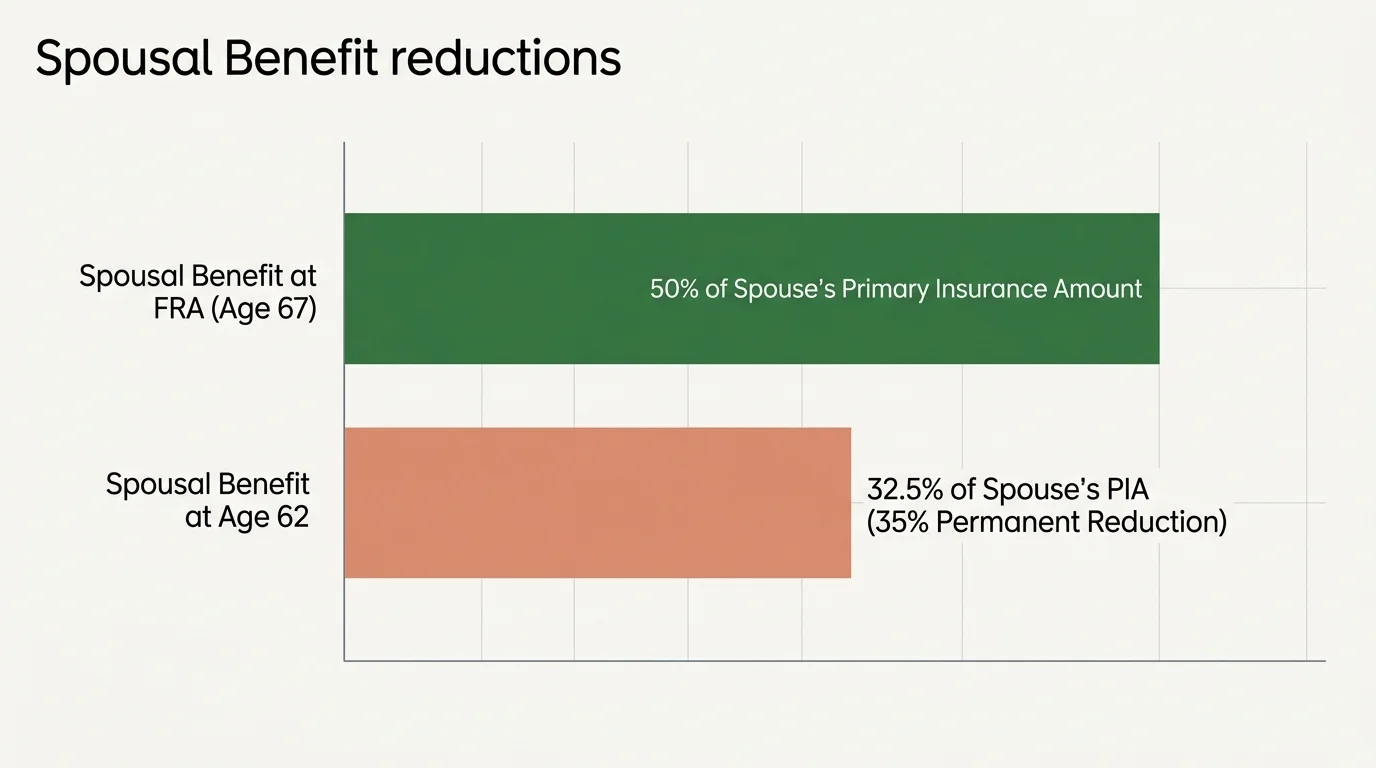
Spousal benefits allow you to claim up to 50% of your spouse’s Primary Insurance Amount if you file at your own Full Retirement Age. However, claiming spousal benefits at age 62 when your FRA is 67 results in a permanent 35% reduction in that spousal payout. Instead of receiving 50% of your partner’s baseline benefit, your check drops permanently to 32.5% of their PIA. This reduction applies even if your spouse earned a high lifetime income and is already collecting their own maximum payout.
Unlike personal retirement benefits, spousal benefits do not earn delayed retirement credits if you wait past your FRA. However, filing before FRA forever caps the benefit percentage you receive. Before submitting a spousal claim early, calculate the compounded impact on your household cash flow. Coordinating claim timing with your partner ensures your family captures maximum lifetime distributions without locking in avoidable discounts.